 Integrity and Accountability
CARBON CREDIT LEGAL STATUS
Lever last updated: 10 September 2026
Legislation or guidance clarifying what legal rights a carbon credit holder actually has.
Cost
Very low to Low
Authorities pay for specialist legal analysis, consultation, drafting and guidance. Clarifying one issue costs less than coordinating reforms across property, insolvency, tax and financial regulation.
Complexity
Low to High
Clarifying existing law through guidance is relatively simple. New property rights require legislation; reconciling these with insolvency, registry operations and financial regulation can involve several authorities.
Timeline
Short to Medium
A reasonable planning range is one to two years for a focused clarification to change contracts or transfers, and two to five years for broader reforms to affect transactions and financing.
Integrity, Transparency & MRV
Innovation & Cost Reduction
Social & Environmental Safeguards
Energy, Transport & Storage Infrastructure
Inputs & Capacity
Demand Formation
Bankability and Cost of Capital
Policy Architecture & Coordination
Overview
Governments can define carbon credits' legal status through legislation or regulation, and clarify how existing law applies through authoritative guidance. The intervention establishes what rights a holder acquires and how they are protected when credits are sold, pledged as security for a loan, retired or disputed. Without clear rules, buyers may not know whether they own an asset or only have a contractual claim against a seller. Resolving that uncertainty gives buyers and lenders firmer grounds to transact with CDR suppliers. Legal status can also specify financial regulation and permitted compliance uses. Those decisions are distinct from ownership, certification of removal quality and registry operation.
Key Considerations
Rules should follow actual transactions rather than simply declare credits to be “property”. Lawmakers need to specify when a credit exists, whether registration establishes ownership, and how rights pass to buyers. They should clarify who is entitled to customer credits if a broker becomes insolvent, lenders' priority over pledged units, and remedies after fraud or incorrect transfers. Issued credits remain distinct from land, stored CO₂ and promises of future delivery. Tax, accounting, financial regulation and permitted climate claims require consistent treatment, while cross-border trades need clarity about which country's law governs competing claims.
Opportunities
Clear ownership and transfer rules can reduce repeated legal negotiations and make standard contracts easier to use. Buyers can establish what they receive, and lenders can assess whether credits offer enforceable security. Predictable insolvency treatment clarifies whether an intermediary's creditors can claim its customers' assets. Regulatory classification identifies applicable trading protections, while specified compliance recognition can connect eligible units to buyers already subject to an obligation. These changes remove legal obstacles to sales and financing without guaranteeing future prices or successful removal delivery.
Risks
An incomplete definition may leave losses after fraud, cancellation or intermediary failure unresolved. Protecting innocent buyers can shift losses to previous holders, so that allocation needs to be explicit. Financial-market rules can impose disproportionate burdens on small suppliers, while exemptions may remove useful protections. Conflicting national rules can create competing ownership claims, and retrospective changes can unsettle contracts. Legal recognition must not imply that a credit represents high-quality CDR or permits unrestricted climate claims.
Monitoring and Evaluation
Evaluation should examine whether participants can establish ownership, complete transfers and enforce their rights with fewer disputes and delays. Fraud, registry errors and insolvencies can reveal remaining gaps. Collateral use and transactions through the intended compliance route provide useful evidence, while price and demand conditions also affect financing. Recurring uncertainty across courts, regulators or registries should guide amendments.
Stakeholder Engagement
Registry operators and intermediaries should explain actual transactions, while buyers, developers and lenders identify uncertainties that obstruct them. Property and insolvency lawyers, financial regulators, tax authorities and accountants should test consistency across their responsibilities. Landowners and other affected rights-holders need consultation where credit creation depends on their rights, without assuming credit ownership transfers the land or stored carbon.
Governance Levels
National governments can establish general property, commercial and regulatory treatment. Regional or state governments can act where those powers are devolved. Supranational institutions can harmonise treatment within a common market using their assigned powers, while national property and insolvency law may still govern particular rights. International legal principles can support convergence but require domestic implementation to settle ownership between private parties. Registry contracts alone cannot establish a generally binding property regime.
Implementation Strategies
Lawmakers should begin with transactions that are currently difficult or disputed, including sales, advance purchases, loans secured against credits and intermediary insolvency. This identifies which legal questions need intervention and which existing rules already work.
The legal framework should distinguish the issued unit from the underlying project, land, stored carbon and future delivery promise. It should explain the effect of registration, transfer, retirement and cancellation on the rights of holders and other claimants.
Authorities should specify any compliance use and financial-market classification separately from ownership. A credit's acceptance under one programme should not imply acceptance elsewhere or unrestricted permission to make an offsetting claim.
Regulators should agree how their property, insolvency, tax and market-conduct rules interact. Cross-border provisions should identify the applicable law and a route for resolving competing claims.
Transition arrangements should protect reasonable reliance on existing contracts and explain how registries and market participants must adapt. Guidance and model clauses can make the rules usable, with periodic review informed by actual disputes.
Case Studies
Australia’s statutory treatment of Australian Carbon Credit Units
Australia's Carbon Credits (Carbon Farming Initiative) Act 2011 treats an Australian Carbon Credit Unit as personal property and identifies its registered holder as the legal owner. Legal ownership passes through the prescribed registry transfer process. The Act also addresses transfers by will or other operation of law and protects qualifying purchasers who buy in good faith without notice of a defect in the seller's title. These provisions give parties a common answer to what is being sold and when ownership changes, rather than leaving the answer entirely to private contracts. The scheme includes sequestration and emissions-avoidance activities, so the property rules are a carbon-credit precedent rather than proof that every unit represents durable CDR.
Singapore’s legal recognition of credits for carbon-tax compliance
Singapore's National Environment Agency administers the country's carbon tax. Since January 2024, its International Carbon Credit Framework has allowed taxable facilities to use eligible international credits for up to five per cent of their taxable emissions, subject to prescribed requirements. The agency provides procedures for sourcing and surrendering those credits. This gives qualifying units a defined legal use and gives liable companies a reason to purchase them. It illustrates one part of legal status, compliance recognition, rather than a complete ownership regime. Eligibility is broader than CDR, and accepting a credit against Singapore's tax does not settle who owns it under the law governing that credit.
UNIDROIT’s work on the legal nature of verified carbon credits
UNIDROIT, an intergovernmental organisation that develops common private-law rules, is developing principles on the legal nature of verified carbon credits with support from the World Bank Group. Its work addresses creation, ownership, transfer, use as collateral, intermediaries, insolvency and the law applicable to transactions. Following working-group sessions from 2023, draft principles were under public consultation in September 2026, with feedback scheduled for discussion in October. The approach gives governments a common reference for resolving legal uncertainties across markets instead of independently inventing incompatible definitions. These are proposed legal principles, not binding international property law or evidence that financing conditions have already improved. They concern verified credits generally, including both reductions and removals.
European Union voluntary carbon credits and financial regulation
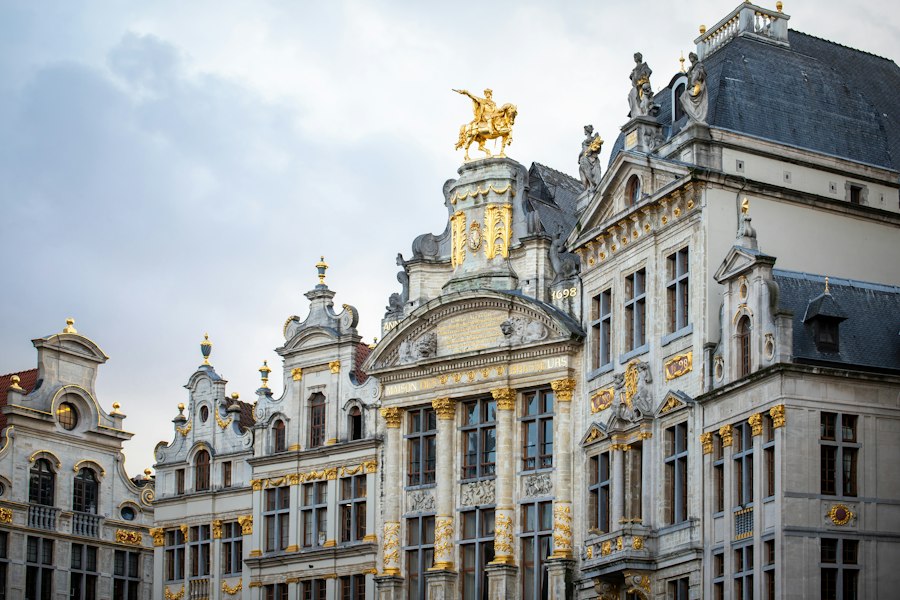
The EU’s Markets in Financial Instruments Directive, known as MiFID II, determines which assets and investment services fall under financial-market supervision. Its classification includes EU Emissions Trading System allowances, while ordinary voluntary carbon credits bought and sold directly generally fall outside it. A broker selling those credits therefore does not normally require MiFID authorisation for that activity alone, and buyers do not automatically receive the protections attached to regulated investment services. The authorisation requirement instead follows the services and instruments covered. Derivatives, meaning contracts whose value depends on those credits, can qualify as financial instruments depending on their structure; this does not change the underlying credit’s classification. For CDR, the case illustrates how lawmakers determine which intermediaries require supervision and which protections buyers receive. Financial classification remains separate from certifying removal quality or establishing ownership rights, and exclusion from MiFID does not mean that other laws cease to apply.
More Integrity and Accountability
Measurement, Reporting and Verification Protocols
A common rulebook specifying how projects must measure, report and verify their removals.
Cost
Very low to Low
Complexity
Low to High
Timeline
Short to Medium
Integrity, Transparency & MRV
3–5Innovation & Cost Reduction
1–2Social & Environmental Safeguards
1–2Energy, Transport & Storage Infrastructure
N/AInputs & Capacity
1–2Demand Formation
1–2Bankability and Cost of Capital
1–2Policy Architecture & Coordination
2–4
Certification schemes
Independent assurance that a removal project and its results meet defined quality standards.
Cost
Very low to Medium
Complexity
Low to High
Timeline
Short to Medium
Integrity, Transparency & MRV
3–4Innovation & Cost Reduction
1–2Social & Environmental Safeguards
2–4Energy, Transport & Storage Infrastructure
N/AInputs & Capacity
1–2Demand Formation
1–2Bankability and Cost of Capital
1–3Policy Architecture & Coordination
2–4
Financial Accounting for Removal Assets and Obligations
Accounting rules clarifying how companies record removal credits and obligations in financial statements.
Cost
Very low to Low
Complexity
Low to Medium
Timeline
Short to Medium
Integrity, Transparency & MRV
1–2Innovation & Cost Reduction
N/ASocial & Environmental Safeguards
N/AEnergy, Transport & Storage Infrastructure
N/AInputs & Capacity
N/ADemand Formation
1–2Bankability and Cost of Capital
1–2Policy Architecture & Coordination
2–3©2026 Alexander Mäkelä and Carbon Gap.
Except where otherwise indicated, this work is licensed under the Creative Commons Attribution–NonCommercial–ShareAlike 4.0 International Licence.
Headline and barrier scores based on Carbon Gap analysis.